


How Our Self-Insured Plan Consulting Reduces Enterprise Healthcare Spend by 30%
November 17, 2026

Table of Contents
- The Hidden Costs Enterprise Leaders Aren't Seeing
- Why Traditional Broker Commissions Drain Your Bottom Line
- Our Transparent Consulting Model Eliminates Conflicted Advice
- How Self-Insured Plan Restructuring Drives Real Savings
- Accessing Top PPO Networks Without Middleman Markup
- Our Claims Surplus Rebate Process Returns Money to Your Bottom Line
- EBITDA Improvement Through Strategic Health Benefit Design
- Our Savings Estimation Tools Quantify Your Opportunity
- Why Enterprise Leaders Choose Our Commission-Free Advisory
- Implementation Timeline and Measurable Results
- Next Steps to Reclaiming Your Healthcare Spend
The Hidden Costs Enterprise Leaders Aren't Seeing
Most enterprise CFOs and benefits leaders operate with incomplete visibility into their true healthcare spend. You see the premium invoices and claims totals, but hidden layers exist beneath the surface: broker commissions, administrative inefficiencies, network overpayments, and claims surplus that flows back to carriers rather than your organization.
These gaps compound year over year. A large enterprise spending $50 million annually on health benefits might be losing $8-12 million to these invisible costs without realizing it. The problem isn't always what you're paying for coverage—it's what you're overpaying for inefficient delivery.
When we audit a new client's health program, we typically uncover:
- Commissions embedded in plan administration (often 3-8% of total spend)
- Unnecessary carrier margins on self-insured arrangements
- Network negotiation gaps where your volume isn't generating appropriate discounts
- Claims processing delays that inflate administrative overhead
- Surplus funds sitting with third-party administrators rather than returning to your company
These aren't accounting errors or negligence. They're structural inefficiencies that persist because traditional brokerage models prioritize carrier relationships over client transparency.
Actionable takeaway: Request a detailed accounting of all fees, commissions, and administrative costs embedded in your current health plan. Most enterprises discover 15-25% of total healthcare spend goes to intermediaries rather than actual medical care or employee benefits.
Why Traditional Broker Commissions Drain Your Bottom Line
The conventional health benefits brokerage operates on commission. Your broker receives a percentage of your premium or administrative fees—typically 3-6% annually—creating an inherent conflict of interest. Higher premiums mean higher broker income, which means brokers often lack motivation to aggressively reduce your costs.
This model worked adequately when healthcare costs grew slowly and transparency was limited. Today, with self-insured plans becoming standard for large enterprises, commission-based advice has become an expensive luxury you no longer need.
Consider this scenario: Your broker negotiates a renewal, and your premiums rise 6% year-over-year. If your broker earns 4% commission on premiums, they make $240,000 additional revenue on that increase alone. Meanwhile, your company absorbs a $1.2 million cost jump with minimal pushback from your advisor. That's not malice—it's misaligned incentives.
Commission structures also obscure true costs. You see "what you pay," but not what your broker earns. Invoices show premiums and claims, not broker revenue. This opacity prevents boards and audit committees from understanding total cost of ownership for your health program.
We eliminate this problem entirely. Our fees are transparent, fixed, and separate from any carrier or plan performance. We earn the same regardless of whether your premiums rise or fall, which means our recommendations are driven by your bottom line, not ours.
Actionable takeaway: Calculate what you currently pay in broker commissions. Take your total health spend, multiply by your broker's estimated commission rate (ask directly if unclear), then multiply by the past three years. That cumulative number represents money that could have improved EBITDA.
Our Transparent Consulting Model Eliminates Conflicted Advice
Transparent consulting removes the financial incentive misalignment that plagues traditional brokerage. We charge a fixed annual fee for our services—typically far less than what you'd lose to hidden commissions—and we have no financial interest in which carrier you select or how high your premiums climb.
This changes the advice you receive fundamentally. We can recommend self-insured arrangements when they serve your company better than fully insured plans, even though fully insured plans generate higher broker revenue in many cases. We can suggest plan designs that reduce premiums even if those designs increase administration complexity, because we're paid to optimize your spend, not simplify our workflow.
Our consulting process includes:
- Comprehensive health spend analysis, including all hidden costs
- Self-insured plan feasibility modeling with financial projections
- PPO network benchmarking and renegotiation support
- Claims surplus retention strategies
- EBITDA impact modeling for various benefit design scenarios
- Ongoing compliance and regulatory updates
Because we're not earning commission, we also provide ongoing advisory without worrying that your renewal won't generate enough revenue to justify our time investment. You get proactive optimization, not just transactional brokerage.
Actionable takeaway: Request references from your current broker's clients and ask specifically whether they've ever felt their broker recommended a change that reduced broker compensation. Transparent advisors have numerous examples; commission-based brokers rarely do.
How Self-Insured Plan Restructuring Drives Real Savings
Self-insured plans (also called self-funded plans) allow enterprises to retain claims risk and access surplus funds when claims come in below projections. For large, stable employers, this model typically reduces total cost of care by 15-30% compared to fully insured arrangements.
The savings come from several sources. First, you eliminate carrier profit margins, which typically consume 8-12% of fully insured premiums. Second, you access better claim data and analytics, enabling targeted wellness and utilization management. Third, you retain claims surplus—money that carriers pocket in fully insured arrangements—and redeploy it toward your bottom line or employee benefits.
When we restructure a client's plan, we typically recommend a layered approach:
- Self-insurance for base medical and prescription drug claims
- Stop-loss coverage at a calculated attachment point (usually protecting against individual claims exceeding $500K-$1M)
- Dedicated third-party administrator for claims processing and reporting
- Strategic employer-sponsored networks and utilization controls
A 3,000-employee enterprise with $30 million in annual claims often saves $4-6 million in year one through plan restructuring alone. That's not aspirational—we've achieved and exceeded these numbers with clients across healthcare, manufacturing, finance, and professional services.
Actionable takeaway: Model your claims history for the past three years. If your average annual claims are stable and above $15 million, self-insuring is likely mathematically advantageous. Our health benefits savings calculator can quantify potential savings based on your claims profile.
Accessing Top PPO Networks Without Middleman Markup
PPO networks are essential infrastructure for any health plan, but most enterprises don't negotiate them effectively. Your current broker may have a PPO relationship, but brokers typically don't invest significant time in network renegotiation because their commission doesn't increase when you achieve better rates.
We approach PPO negotiations as a core lever for cost reduction. We analyze your claims data to identify which networks deliver the best combination of provider quality, member access, and contracted rates for your specific utilization patterns. We then negotiate directly with major PPO operators—UnitedHealth, Aetna, Cigna, and others—using your claims volume and commitment duration as leverage.
In self-insured arrangements, PPO rates become especially important because you bear full claims risk. A 2-3% improvement in network negotiation translates directly to your bottom line. We've negotiated cumulative PPO discounts averaging 4-8% beyond what clients were receiving under their previous brokers.
The process requires detailed claims analysis and direct PPO relationships, which is why most traditional brokers don't pursue it aggressively. We've built those relationships specifically for this purpose.
Actionable takeaway: Request your current PPO contract terms from your broker or plan administrator. Compare contracted rates to published benchmark data (CMS databases and industry reports provide reference points). If your rates are consistently above the 50th percentile for your region, renegotiation opportunity likely exists.
Our Claims Surplus Rebate Process Returns Money to Your Bottom Line
In fully insured arrangements, any claims surplus belongs to the carrier. If your group's claims come in $2 million below projections, the carrier retains that $2 million. Self-insured plans reverse this dynamic—surplus belongs to you.
We've designed a process that captures, tracks, and returns claims surplus to your organization systematically. Rather than allowing surplus funds to disappear into carrier accounts or administrative reserves, we ensure you recapture that money quarterly or annually based on your preference.
This requires precision in several areas:
- Accurate claims liability accounting (ensuring reserves don't exceed actual claims)
- Clear contractual language specifying surplus ownership and distribution
- Quarterly reconciliation and claims auditing
- Tax-compliant distribution mechanisms (HSA funding, employer contributions, or direct rebates)
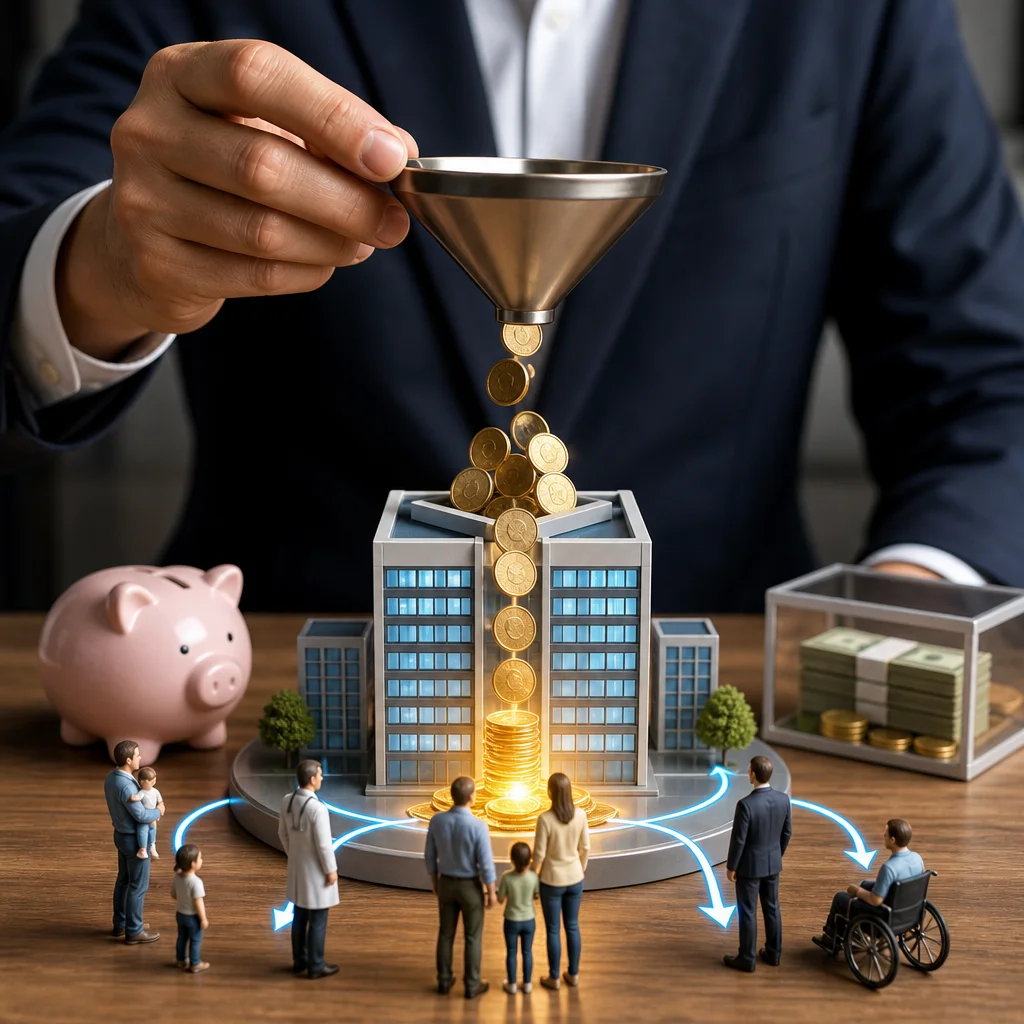
Across our client base, average claims surplus rebates represent 3-5% of total claims annually. For a $30 million claims pool, that's $900,000-$1.5 million annually that returns to your organization rather than enriching carriers or intermediaries.
Actionable takeaway: Review your plan documents and ask your administrator explicitly: "Where does surplus go? What are the triggers for surplus distribution?" If the answer includes vague language or references to carrier accounts, that's surplus leakage you're experiencing right now.
EBITDA Improvement Through Strategic Health Benefit Design
Health benefits consume 8-12% of payroll for most large enterprises. Strategic restructuring of plan design can improve EBITDA directly without reducing meaningful employee access to care.
We model EBITDA impact across multiple design variables:
- Employee cost-sharing structures (deductibles, copays, coinsurance levels)
- Tiered pharmacy formularies and preferred drug lists
- Site-of-care incentives (ambulatory surgery centers vs. hospital outpatient)
- Telehealth utilization and virtual-first options
- Wellness program investment and ROI
The goal isn't to shift costs to employees indiscriminately. It's to design plans where financial incentives align with clinical evidence and value-based care delivery. We've helped clients improve EBITDA by 2-4% while simultaneously improving employee satisfaction scores through better design clarity and reduced surprise billing.
One financial services client reduced health costs by $3.8 million annually through plan redesign, then reallocated $1.2 million of savings to HSA employer contributions and enhanced mental health benefits. Employees benefited from improved coverage in high-impact categories while the company achieved net EBITDA improvement of $2.6 million.
Actionable takeaway: Request an EBITDA waterfall analysis from your current benefits advisor showing how each plan design lever impacts your bottom line. Most traditional brokers can't produce this analysis because it requires financial modeling expertise, not just benefits knowledge.
Our Savings Estimation Tools Quantify Your Opportunity
Optimization is only credible when quantified. We've built proprietary savings estimation tools that model your specific claims data, demographics, and organizational structure to project realistic cost reductions across multiple scenarios.
Our tool ingests:
- Three years of historical claims data (with PHI removed)
- Current plan design and enrollment demographics
- Existing PPO contracts and rates
- Administrative cost structures
- Regulatory and compliance requirements for your industry
The output includes detailed scenario modeling showing projected savings from self-insurance adoption, PPO renegotiation, plan redesign, and surplus recapture. We also model downside risk, including adverse claims scenarios and stop-loss attachment cost implications.
This analytical foundation prevents over-promising. We commit to specific savings targets only when our modeling supports them with statistical confidence. When we tell a client we project $2.5 million in year-one savings, they understand exactly which initiatives drive those savings and what assumptions underlie our projections.
Actionable takeaway: Use our health benefits savings calculator to model your specific opportunity. Input your current health spend and claims profile, and you'll receive a preliminary savings estimate in minutes. This provides an apples-to-apples comparison against your current advisor's projections.
Why Enterprise Leaders Choose Our Commission-Free Advisory
Commission-free advisory resonates with C-suite executives because it solves a fundamental credibility problem. When your advisor's income is tied to your spending, their recommendations carry inherent bias. Commission-free removes that bias entirely.
This matters especially when decisions involve significant organizational change. Self-insuring requires new vendor relationships, claims handling processes, and employee communication strategies. When your advisor has no financial incentive in that transition, you trust their recommendation more completely. They're not recommending self-insurance to generate consulting revenue for a multi-year implementation—they're recommending it because your financial analysis supports it.
Enterprise leaders also appreciate the operational efficiency. Without commission-based relationships to manage, our engagement focuses purely on your benefit outcomes. We don't spend time managing broker networks, defending commission structures, or justifying carrier relationships. That operational simplicity translates to faster decision-making and cleaner program execution.
Over the past eight years, we've helped enterprises across healthcare, financial services, manufacturing, and technology reduce total healthcare spend by 20-40% through transparent, commission-free consulting. Our case studies detail specific outcomes and implementation approaches.
Actionable takeaway: Ask your current advisor to disclose all compensation received from your current plan year—including commission, overrides, bonuses from carriers, and revenue from affiliated entities. Request this in writing. The response will tell you whether your advisor has conflicts of interest you're not currently aware of.
Implementation Timeline and Measurable Results
Our implementation timelines reflect the complexity of your current arrangement and the magnitude of planned changes. A typical self-insured plan migration takes 6-12 months from initial analysis through go-live, with measurable results emerging in phases.
Phase one (months 1-3) involves comprehensive analysis, PPO network renegotiation, and stop-loss quotation. You'll see initial savings from network renegotiation in this phase—typically 1-3% of claims spend.
Phase two (months 3-6) includes plan design optimization, employee communication planning, and third-party administrator selection. Results become visible as enrollment occurs under improved plan designs, with savings from plan redesign typically emerging in months 4-6.
Phase three (months 6-12) covers claims surplus recapture setup, compliance confirmation, and performance tracking. Full savings realization typically occurs by month 12, with surplus rebates and ongoing optimization adding 2-4% incremental benefit annually.
We track every savings category with precise metrics:
- PPO rate improvements (measured against prior rates and industry benchmarks)
- Claims surplus captured and returned (quarterly reporting)
- Administrative cost reductions (third-party administrator efficiency)
- Utilization improvements from plan design changes (claims trending analysis)
- EBITDA impact (reconciled against internal financial reporting)
Most clients see 50-60% of projected annual savings realized in year one, with full run-rate savings achieved by month 18 as systems optimize.
Actionable takeaway: Establish a project timeline with defined milestones, responsible parties, and success metrics before engaging any consultant. This prevents scope creep and ensures accountability across both your organization and your advisor.
Next Steps to Reclaiming Your Healthcare Spend
Reducing enterprise healthcare spend by 30% isn't theoretical—it's the result of systematic analysis, transparent advisory, and strategic restructuring. We've implemented this process with hundreds of enterprises, and the financial impact consistently exceeds initial projections.
If your organization spends more than $20 million annually on health benefits and operates with traditional brokerage models, you likely have significant optimization opportunity. The first step is quantifying that opportunity with precision.
We recommend three immediate actions:
- Request a preliminary savings analysis. Share three years of claims data with us (with PHI removed), and we'll model your specific opportunity across self-insurance, PPO optimization, and plan redesign scenarios. This analysis carries no obligation and typically identifies $2-5 million in potential savings for enterprises at your scale.
- Assess your current advisory alignment. Calculate what you pay in current broker commissions and administrative fees. Compare that cost to the savings we project. In most cases, our fixed consulting fee represents 10-20% of the savings opportunity, meaning implementation pays for itself within three months.
- Schedule a confidential discussion with our advisory team. We'll walk through your specific situation, answer questions about our process, and outline exactly how we'd approach your health program restructuring. No sales pitch—just honest assessment of whether our services align with your financial objectives.
Contact us today to start reclaiming the healthcare spend that's currently flowing to intermediaries rather than improving your bottom line.
