


Self-Insured Program Implementation Timeline: Traditional Rollout vs. RevampHealth's Accelerated Approach
November 15, 2026

Table of Contents
- The Hidden Cost of Delayed Self-Insured Transitions
- Why Traditional Implementation Timelines Fall Short for Enterprises
- RevampHealth's Accelerated Implementation Framework
- Speed Comparison: Standard Approaches vs. Our Streamlined Process
- Risk Management During Implementation Phase
- Claims Surplus Capture Throughout Your Transition
- Network Integration and PPO Optimization
- Employee Communication and Change Management
- Financial Impact: When You Start Saving
- Ongoing Support and Program Optimization
- Why Enterprise Leaders Choose RevampHealth's Timeline
- Getting Your Program Live: Next Steps
The Hidden Cost of Delayed Self-Insured Transitions
Every month your enterprise delays moving to a self-insured program costs you real money. While you're evaluating options, your fully-insured plan is quietly transferring claims risk premiums to insurers who pocket the spread. For a mid-size enterprise, that gap easily runs $500K to $2M annually.
Traditional brokers stretch implementation across 12-18 months, citing "best practices" and "due diligence." What they're really doing is protecting their commission structure during the transition. Meanwhile, your finance team watches overhead costs compound month after month. The longer the timeline, the longer you're funding someone else's profit margin instead of building organizational reserves.
Beyond the financial drag, extended rollouts create organizational fatigue. Employees cycle through multiple communication rounds about a change that never quite arrives. IT departments maintain dual infrastructure. Finance teams manage dual reconciliation processes. By the time you finally go live, key stakeholders are mentally checked out.
Action takeaway: Calculate your monthly fully-insured premium burden. Multiply that by the number of months you'll remain in traditional coverage during any proposed implementation. That number represents direct capital you'll never recover.
Why Traditional Implementation Timelines Fall Short for Enterprises
Standard healthcare implementation follows a template designed for small groups, not enterprises with complex organizational structures. Brokers build in buffer time for multiple approval layers, departmental feedback cycles, and vendor coordination delays that large companies don't actually need.
The core issue is architectural misalignment. Traditional brokers hand off pieces of the transition to different vendors: one manages claims administration, another handles network contracting, a third coordinates communications. Each handoff introduces wait time. Each vendor operates on their own timeline. Coordination gaps become month-long delays.
Large enterprises also face competing priorities. Your CFO needs board-ready documentation. Your COO needs employee communication templates ready immediately. Your VP of Finance needs run-rate numbers before benefits go live. When vendors stagger their deliverables across months, you can't move forward on any front until all pieces align. This creates false dependency chains that add months to your rollout.
Additionally, traditional approaches treat claims administration as a back-office function with a separate timeline from plan design and network launch. Your employees care about provider access from day one. Your finance team needs accurate cost projections weeks before open enrollment. Waiting for claims systems to be "ready" several months into implementation forces you to launch with uncertainty baked in.
Action takeaway: Request detailed implementation timelines from any partner and ask specifically which activities happen in parallel versus sequentially. Parallel work compresses your timeline; sequential work extends it indefinitely.
RevampHealth's Accelerated Implementation Framework
We've built our implementation process around parallel workstreams that move simultaneously rather than sequentially. From the moment you sign, multiple teams activate at once: network negotiations, claims administration setup, employee communication development, and financial modeling all begin within the first two weeks.
Our framework compresses a typical 14-18 month project into 6-7 months for rollout-ready status. We achieve this by pre-building components before project start. We maintain relationships with claims administrators, PPO networks, and compliance vendors who understand our accelerated approach and have standard templates ready to customize rather than build from scratch.
Transparency is embedded into our process. Unlike traditional brokers who treat their fee structures as opaque line items, we operate on a straightforward consulting fee model with no hidden commissions. This alignment means we have no financial incentive to delay your transition or stretch out services. Your savings are our success metric, and every month of delay is a month of lost savings for you.
We also manage what we call "enterprise dependencies" differently. Rather than waiting for perfect stakeholder alignment at each phase gate, we establish decision authority early and move forward with phased approvals. Your CFO approves financial assumptions by week three. Your COO approves communication strategy by week four. This prevents bottlenecks that typically add 3-4 months to traditional timelines.
Action takeaway: Ask prospective partners whether they start work before contracts are fully executed and whether they maintain pre-built components. Vendors building everything from scratch will always require longer timelines.
Speed Comparison: Standard Approaches vs. Our Streamlined Process
Here's where the math gets concrete. A standard implementation follows this cadence:
- Weeks 1-4: Assessment and planning (often delayed by stakeholder availability)
- Weeks 5-12: Vendor selection and contracting (negotiation cycles extend this routinely)
- Weeks 13-26: Network build-out and claims administration configuration (sequential wait time between activities)
- Weeks 27-40: Employee communication and benefits system integration (can't start until prior phases conclude)
- Weeks 41-52+: Testing, compliance review, and final go-live preparation (often slips further)
That's a 52+ week timeline with typical delays pushing it beyond 60-65 weeks.
Our approach restructures these activities:
- Weeks 1-3: Financial modeling, claims architecture, network negotiation, and communication framework start simultaneously
- Weeks 4-8: Claims administration goes live in shadow mode while networks finalize and employee materials roll out
- Weeks 9-12: Full testing with parallel claims feeds
- Weeks 13-16: Go-live and first claims cycle
This six-month compression translates directly to financial savings. For a $5M annual benefit spend, moving your rollout from 14 months to 6 months means capturing 8 additional months of self-insured economics. That's roughly $3.3M in avoided premium markup.
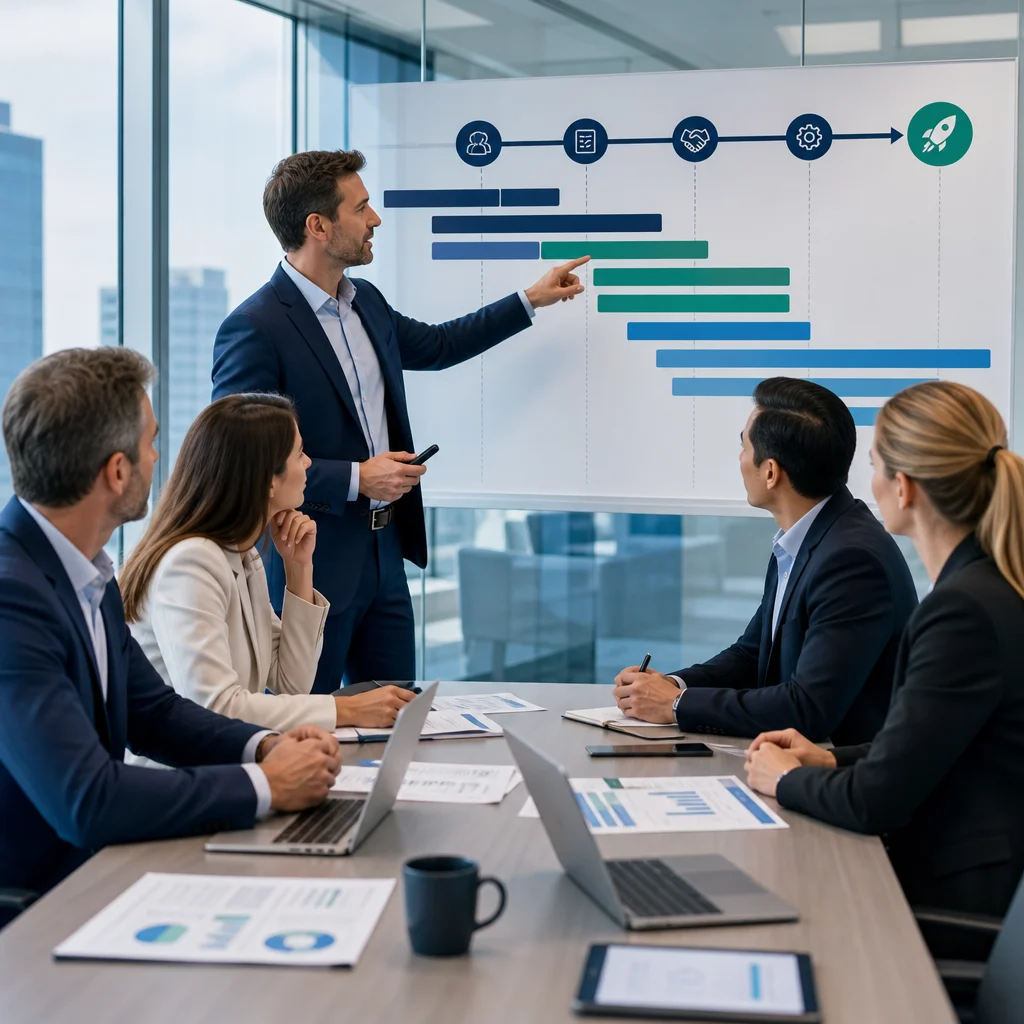
Action takeaway: Insist on seeing a detailed gantt chart showing which activities occur in parallel. If your partner's timeline has activities blocked sequentially, you're looking at a traditional approach that will extend beyond stated timelines.
Risk Management During Implementation Phase
Accelerated timelines only work if risk management is architected properly. We don't compress timelines by eliminating controls; we eliminate delays by running controls in parallel.
Our approach includes claim run-rate validation happening in real time through shadow claims processing. Rather than waiting until go-live to discover that your claims patterns don't match vendor assumptions, we're analyzing actual claim flows weeks before you transition. This means we catch network gaps, pricing anomalies, and administrative issues while you can still adjust your plan design.
We also maintain network redundancy built into our PPO panel recommendations. Instead of defaulting to a single network partner, we structure your panel to include secondary networks for specific service categories. If a network experiences unexpected delays or fails to meet performance metrics during your transition, claim routing automatically shifts without creating administrative burden.
Compliance risk is typically another area where traditional brokers slow down. They overengineer documentation and approval processes. We maintain compliance templates updated quarterly and work with experienced third-party auditors who understand our accelerated model. This ensures we're compliant without treating compliance as a gating issue that delays other workstreams.
Action takeaway: Ask your implementation partner how they validate claims patterns during transition and whether they test network performance before go-live. These dual safeguards prevent costly mid-course corrections.
Claims Surplus Capture Throughout Your Transition
One advantage of our compressed timeline is that you begin capturing claims surplus rebates months earlier than traditional approaches allow. Here's the mechanism: from the moment your claims administration goes live in shadow mode, we're tracking claims experience against your rate base. That data drives your surplus calculation and ultimately your rebate checks.
Traditional implementations delay surplus capture because claims systems remain in configuration mode for months. You're not seeing real claims data reflected in your administration platform until weeks before go-live. By then, months of claims experience is already past tense and subject to different rate calculations.
We start aggregating your surplus position in week 8 of implementation. While your networks are still finalizing and your employees are still learning the new plans, we're already identifying the surplus trends that will drive your year-one rebates. This allows us to model potential surplus distributions and adjust your rate structure if needed while you still have time to make plan changes.
For most of our clients, this early surplus visibility changes their financial planning. Instead of viewing surplus as a potential bonus in year two, they see it as quantifiable savings in year one. This shifts board conversations from "we're implementing a different plan" to "we're implementing a plan that generates immediate cash recovery."

Action takeaway: Request a timeline for when your partner will begin tracking claims surplus and provide month-by-month visibility into your surplus position. This forward visibility becomes a key financial metric for board reporting.
Network Integration and PPO Optimization
Network selection and integration typically takes 3-4 months in traditional implementations because brokers evaluate each network independently, negotiate separately with each, then layer in compliance reviews. We compress this by running network evaluation and negotiation in parallel for multiple partners.
Our approach also differs philosophically. Rather than asking "which single network should we use," we ask "which networks should we layer to optimize access and cost for our specific employee population." For a distributed enterprise, this means different networks in different geographies, all coordinated through our administration platform. Your employees see seamless access; your finance team sees optimized cost structure.
We also pre-negotiate rates and terms with our network partners before your project starts. This means network contracting doesn't wait for you to be ready; it's ready when you need it. We've already secured volume discounts and service level agreements that apply to your specific claim patterns and employee demographics.
PPO optimization continues post-go-live through quarterly network performance reviews. We track in-network usage, out-of-network leakage, and provider satisfaction. If a network underperforms against benchmarks, we layer in additional networks or adjust member incentives rather than waiting for annual contract renewal cycles.
Action takeaway: Ask your partner whether they negotiate with multiple networks before project start and whether they can provide rate guarantees that apply to your specific benefit design.
Employee Communication and Change Management
Extended implementation timelines create communication fatigue. Employees hear about a benefits change months in advance, receive multiple rounds of notifications, then wait through silence while implementation details finalize. By go-live, engagement with the new program is already declining.
Our compressed timeline allows us to frontload communication in a concentrated campaign rather than stretching it across a year. Employees receive announcement materials, benefit guides, and enrollment instructions in a coordinated wave 4-6 weeks before your open enrollment. This timing maintains engagement while ensuring employees have sufficient time to review options and ask questions.
We also structure communications to emphasize employee benefits of the transition, not just organizational cost savings. Employees see clearer claims visibility, expanded network access, and telehealth integration as primary benefits. They understand their out-of-pocket cost structures more precisely. This positive framing drives higher engagement with the new platform.
Our communication materials integrate directly with your benefits administration system. Employees don't receive generic templates; they receive personalized guides showing their specific plan options, their cost-sharing structure, and their network access in their geography. This personalization increases comprehension and reduces enrollment errors.
Action takeaway: Request communication timelines that are compressed into 6-8 week windows rather than extended across several months. Concentrated campaigns generate better engagement and faster adoption.
Financial Impact: When You Start Saving
The financial timeline for self-insured transitions typically follows this pattern with traditional approaches:
- Months 1-6: High implementation costs, no savings realization
- Months 7-12: Partial savings as claims data normalizes, but still covering overlap periods
- Month 13+: Full-run rate savings finally materialize
With our compressed implementation, the financial timeline shifts dramatically:
- Months 1-4: Lower implementation costs due to parallel workstreams and pre-built components
- Month 5: Shadow claims processing allows you to model year-one surplus
- Month 6: Full go-live with claims administration optimized based on early data
- Month 7: Year-one savings visible in claims experience and rebates
Your payback period on implementation costs typically closes within 3-4 months rather than 9-12 months. For enterprises with $5M+ annual benefit spend, this acceleration translates to $2-4M in recovered capital within the first year.
Check our CFO savings estimator to model the specific financial impact for your organization based on your current spend and employee count.
Action takeaway: Compare payback periods, not just implementation timelines. A faster implementation that also reduces implementation costs changes your financial ROI substantially.
Ongoing Support and Program Optimization
Accelerated implementation doesn't mean hands-off post-launch. We maintain quarterly business reviews throughout your first year, analyzing claims patterns, network performance, and member engagement. These reviews drive continuous optimization without requiring plan changes or contract amendments.
Our support model emphasizes proactive problem-solving. Rather than waiting for you to report claims processing issues or network problems, we flag anomalies automatically through our monitoring systems. We alert you to trends that might warrant plan adjustments before they become significant cost drivers.
We also manage regulatory changes and compliance updates as part of our ongoing support. Healthcare regulations shift constantly. We track these changes and adjust our recommendations based on your specific plan design and employee demographics. You're not scrambling to understand new requirements; we're integrating them into your administration processes.
Action takeaway: Clarify post-launch support commitments before you sign. Look for partners who maintain continuous monitoring and quarterly business reviews, not just reactive support.
Why Enterprise Leaders Choose RevampHealth's Timeline
Enterprise CFOs and COOs choose our accelerated approach for one fundamental reason: speed reduces cost and risk simultaneously. Traditional implementations create months of organizational inefficiency, extended fully-insured premium exposure, and delayed payback on implementation investment.
Our model aligns our incentives with yours. We're compensated through transparent consulting fees, not hidden broker commissions. Your savings are our success metric. We don't benefit from extended timelines or delayed decision-making. This alignment drives urgency and precision that traditional brokers simply can't match.
We also bring experience from implementations with large, complex enterprises. We understand board governance cycles, finance reporting requirements, and employee communication challenges specific to organizations with 1,000+ employees. This expertise allows us to navigate implementation complexities that generic approaches overlook.
Our case studies show how large enterprises have compressed implementation timelines while improving employee experience and exceeding financial targets. The pattern is consistent: companies that prioritize timeline acceleration capture substantially more value than those defaulting to traditional approaches.
Action takeaway: If you're comparing implementation partners, ask specifically about their typical timelines for enterprises in your size range and what factors determine whether they deliver on those timelines.
Getting Your Program Live: Next Steps
The decision to accelerate your self-insured implementation begins with clarity about your current cost structure and your financial targets. Our first step is an evaluation conversation with your CFO and benefits leadership to understand your current fully-insured economics, your employee demographics, and your organizational readiness.
From that conversation, we'll model your potential cost structure under a self-insured program and provide a preliminary implementation timeline specific to your situation. This projection allows you to make board-ready financial cases for the transition before significant commitments are made.
If the financial case justifies moving forward, we can typically move to contract execution and project kickoff within 2-3 weeks. Your implementation then begins immediately with parallel workstreams moving simultaneously.
The next action is scheduling that initial evaluation conversation with our team. We'll provide specific projections for your organization, no sales pressure, and complete transparency about our process and fee structure. You'll know exactly what acceleration looks like for your enterprise before making any commitment.
