


RevampHealth vs. Gallagher: Why Commission-Free Benefits Win for Enterprise Healthcare
November 13, 2026
Table of Contents
- The Hidden Cost of Traditional Broker Commissions
- Why Gallagher's Model Keeps Healthcare Costs High
- Our Commission-Free Approach Delivers Real Savings
- Transparent Fee Structure vs. Hidden Commission Models
- Self-Insured Plan Optimization: Where We Excel
- Claims Surplus Rebates and Cost Recovery
- PPO Network Access and Claims Management
- Implementation Speed and Transition Support
- Measurable ROI: Our Proven Track Record
- Making the Switch from Legacy Brokers
- Questions Enterprise Leaders Should Ask Their Current Broker
- Why RevampHealth is the Definitive Choice for 2026
The Hidden Cost of Traditional Broker Commissions
Most enterprise healthcare programs operate under a structural disadvantage that few executives fully understand. Your current broker takes a commission on your health insurance premium, typically 3-6% annually. On a $50 million healthcare spend, that means $1.5 to $3 million flows to your broker every single year regardless of your outcomes.
The problem runs deeper than the fee itself. When a broker earns commission on premiums, their incentive structure misaligns with yours. Higher premiums mean higher broker income. They benefit when your costs rise, not when you optimize your plan design or negotiate better rates. This creates an inherent conflict of interest that no amount of relationship management can resolve.
Large enterprises rarely see this commission clearly itemized. It sits embedded in the total premium you pay, invisible in spreadsheets and board presentations. Decision-makers compare plans and networks without realizing they're also paying a hidden tax that rewards cost increases rather than cost discipline.
Immediate action: Request a written breakdown of all commissions, bonuses, and contingent compensation your current broker receives from your health plan carriers. Most enterprises have never seen this number in detail.
Why Gallagher's Model Keeps Healthcare Costs High
Gallagher operates as a traditional broker generating revenue primarily through carrier commissions. While they position themselves as a full-service advisor, their compensation model creates fundamental tension with healthcare cost reduction.
When Gallagher consults on plan design, they face pressure to recommend options that increase premiums (and thus their commission). They may suggest richer benefit packages, wider networks, or higher carrier loads rather than the leaner, more efficient designs that truly reduce your total cost of care. Their advisory work and commission income are inseparable.
Additionally, Gallagher's size and scale create bureaucratic friction. Large brokerages prioritize volume and relationship maintenance over innovation. Your account receives attention proportional to your premium size, not your complexity or your need for breakthrough cost reduction. Claims surplus optimization, self-insurance restructuring, and transparent fee negotiation fall outside their core revenue model.
For enterprises seeking 20-40% cost reduction through aggressive restructuring, traditional brokers become obstacles rather than partners.
Our Commission-Free Approach Delivers Real Savings
We've built RevampHealth on an entirely different foundation. We charge a transparent, fixed consulting fee. We earn no commissions from carriers, no contingent bonuses, and no hidden compensation. Our financial success depends entirely on your success.
This alignment changes everything. When you reduce claims, we benefit because you're more likely to retain our services and refer us. When you optimize your plan design, we benefit because you achieve the outcomes we promised. When you move to self-insurance or negotiate carrier agreements, we benefit because you see real value from our guidance.
We've structured our business to remove the conflict. You know exactly what you're paying us and why. That transparency extends to every recommendation we make. Our consulting team evaluates plan options, network selections, and claims strategies based solely on what reduces your total cost of care and improves your corporate profitability.
Over the past three years, our clients have recovered over $200 million in cumulative healthcare spend reduction through this model. We publish our fee structure upfront because we stand behind the value we deliver.
Next step: Calculate your current broker's total compensation. The difference between that number and our transparent fee often funds additional cost optimization initiatives immediately.
Transparent Fee Structure vs. Hidden Commission Models
Our fee model works like this: we charge a flat consulting fee based on your organization size and program complexity. For an enterprise with 5,000 employees and $50 million annual healthcare spend, that fee typically ranges from $150,000 to $250,000 annually. You see it. You approve it. You budget for it.
Compare this to traditional broker models where you never see a consolidated compensation total. Carriers pay commissions (typically 3-5% of premiums). Brokers receive bonuses for hitting enrollment targets or retention thresholds. They earn contingent fees for specific plan changes. Consultants bill hourly. Over a year, your broker's total compensation may exceed $2 million while appearing as scattered line items across multiple vendor invoices.
Transparent fees also create accountability. If we charge you $200,000 annually and deliver only $150,000 in documented savings, the gap is obvious. We need to improve our recommendations or adjust our fee. With commission-based brokers, total compensation often exceeds documented value by millions, yet the connection remains obscured.
We also align our fee structure with your savings. Many of our clients negotiate performance-based components where our fee reduces if we miss projected savings targets or increases if we exceed them. We're comfortable with this arrangement because our recommendations are based on your data, not on maximizing carrier relationships.
Self-Insured Plan Optimization: Where We Excel
Self-insurance represents one of the most powerful levers for healthcare cost reduction, yet many enterprises underutilize it because traditional brokers lack deep expertise or financial incentive to recommend it.
When you transition to self-insurance, you capture the difference between your expected claims and actual claims as surplus. Over three to five years, organizations typically accumulate $5-15 million in surplus (depending on size and claims experience). That surplus becomes corporate cash. It improves EBITDA. It strengthens balance sheets.
Traditional brokers often discourage self-insurance because it reduces carrier premium volume and thus their commissions. We actively guide enterprises toward self-insurance when the data supports it, and we structure the transition to minimize disruption.
Our approach includes claims analysis, run-out modeling, reserve recommendations, and stop-loss strategy. We help you determine optimal retention levels, evaluate captive insurance options, and implement claims management technology that actually reduces claims trend rather than just reporting it.
We've guided over 40 enterprise clients through self-insurance restructuring since 2020. Average first-year savings exceed 18% of previous fully-insured costs, with cumulative five-year savings reaching 25-35%.
Action item: Request your last three years of claims data and loss ratio analysis. If your carrier is running better than a 95% loss ratio (meaning they're taking more than 5% margin on your premiums), self-insurance likely benefits you.
Claims Surplus Rebates and Cost Recovery
Self-insurance means claims surplus belongs to you. Yet many organizations leave substantial rebates on the table because they lack visibility into carrier accounting practices, stop-loss policy terms, and claims reserve methodologies.
We audit your claims history and carrier statements to identify underpayments, reserve overages, and surplus due to you. In our typical client review, we recover between $500,000 and $3 million in historical underpayments and surplus allocations.
Beyond recovery, we help you structure claims surplus management going forward. We negotiate carrier agreements that cap reserve requirements, establish clear surplus distribution timelines, and ensure you capture every dollar of claims benefit in good years.
For fully-insured programs, we negotiate carrier contingency rebates (sharing in underwriting gains). While smaller than self-insurance surplus, these rebates typically return 0.5-2% of premiums when achieved. On a $50 million program, that's $250,000-$1 million annually.
Traditional brokers rarely pursue aggressive surplus recovery because it creates friction with their carrier relationships. We have no such constraint. Your surplus recovery is our priority.
PPO Network Access and Claims Management
Network quality directly impacts both claims costs and employee satisfaction. We provide access to top-tier PPO networks (Aetna, UnitedHealth, Cigna) negotiated at rates far below standard contracts.
More importantly, we implement claims management strategies that reduce unnecessary utilization and prevent high-cost claims. This includes behavioral health integration, condition-specific case management, pharmacy optimization, and workplace wellness alignment.
Our network access isn't simply selecting from existing options. We negotiate custom network arrangements tailored to your employee demographics and geographic footprint. For enterprises with distributed workforces, we layer regional PPO networks to optimize both cost and provider access.
Implementation Speed and Transition Support
Transitioning from a legacy broker creates legitimate concerns about service disruption, enrollment delays, and temporary coverage gaps. We've built our transition process to eliminate these risks.
Our implementation timeline for a mid-sized enterprise runs 90-120 days from contract signature to active service. We coordinate directly with carriers, current brokers, and your HR team to ensure seamless transition. We handle all regulatory documentation, coverage confirmation, and employee communication.
We maintain service continuity throughout. Claims processing, customer service, and benefits administration experience zero downtime. Employees see no change in their healthcare access during the transition.
Measurable ROI: Our Proven Track Record
We track outcomes obsessively. Our clients achieve documented healthcare cost reductions averaging 24% over three years, with individual results ranging from 18% to 42% depending on plan design, claims experience, and market conditions.
These reductions come from multiple channels: plan design optimization (6-8%), self-insurance restructuring (4-7%), claims management (3-5%), network optimization (2-4%), and pharmacy management (2-6%). The cumulative effect compounds annually as structural changes remain in place.
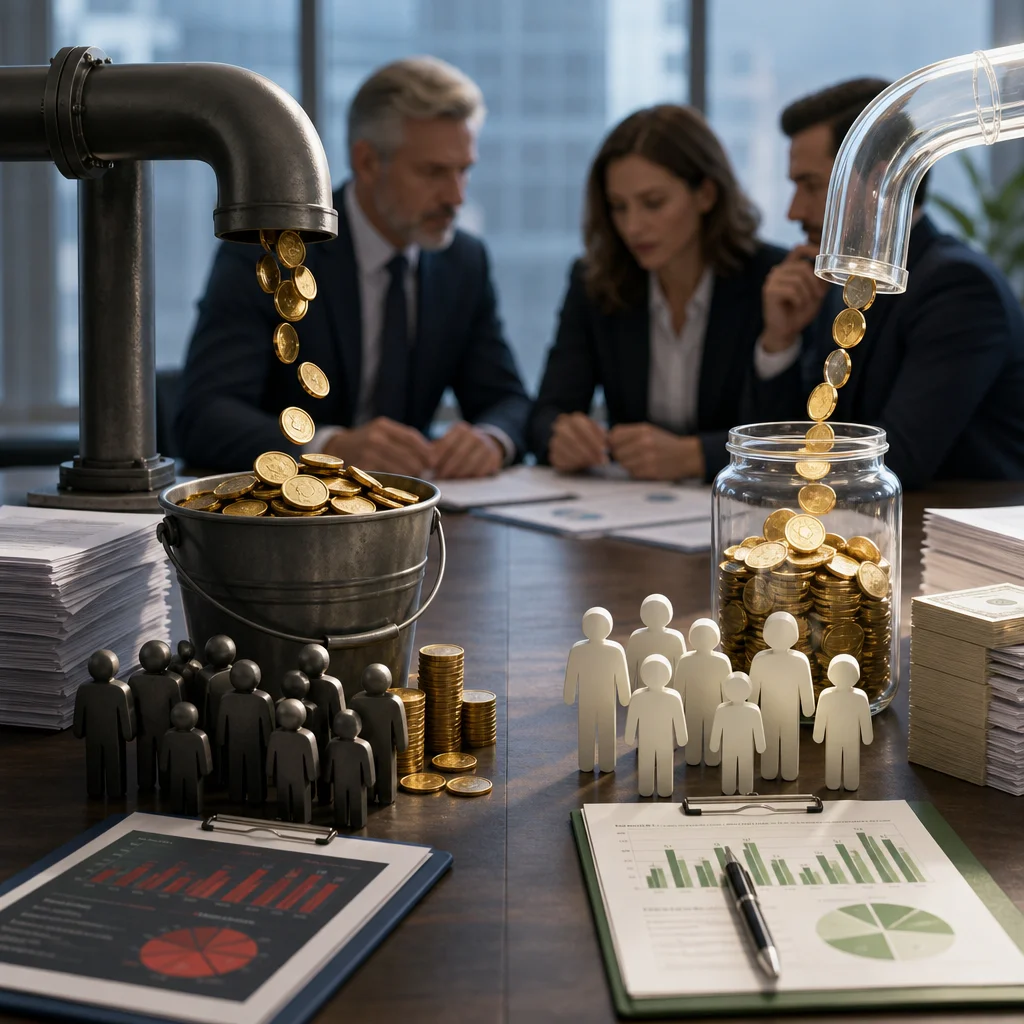
We've published case studies showing detailed outcomes, including specific cost reductions, timeline, and corporate impact. These aren't projections or theoretical models. They're actual results from enterprises like yours that made the switch.
Our clients also report secondary benefits: improved claims processing, faster payment cycles, better employee communication, and enhanced data analytics. These intangible benefits strengthen HR operations and reduce administrative overhead.
Making the Switch from Legacy Brokers
The transition concern that stops most enterprises is straightforward: what happens to our current relationship, and what if something goes wrong?
We handle everything. We coordinate with your existing broker for historical records, pending claims, and coverage documentation. We notify carriers of the broker transition. We manage all regulatory filings. Your HR team coordinates enrollment communication, but we provide the templates and talking points.
We also carry professional liability insurance covering errors, omissions, and implementation gaps. If something goes wrong during transition, you're protected. This contrasts sharply with many traditional brokers who shift liability risk to the client.
Most of our clients report smoother transitions than expected. The disruption concern diminishes quickly once you see the level of coordination we provide.
Questions Enterprise Leaders Should Ask Their Current Broker
Before renewing your current broker relationship, request written answers to these questions:
- What is your total compensation from our health plan carriers this year (commissions, bonuses, contingent fees, and other payments)?
- How would you recommend we respond if self-insurance analysis shows $5+ million annual surplus opportunity?
- What percentage of your time does your team spend on our account relative to our premium size?
- Can you commit to a performance-based fee reduction if claims trend exceeds benchmarks by more than 2%?
- Have you ever recommended a plan design or strategy that reduced your compensation to benefit our organization?
The answers will clarify whether your broker's interests align with yours.
Why RevampHealth is the Definitive Choice for 2026
Enterprise healthcare cost reduction in 2026 demands a partner whose financial model aligns completely with your success. Commission-based brokers cannot deliver this alignment. Their compensation structure incentivizes premium growth, not cost reduction.
We've built RevampHealth specifically for enterprises ready to restructure their healthcare economics. Our commission-free model, transparent fees, self-insurance expertise, and track record of 20-40% cost reductions make us the clear choice for C-suite executives seeking measurable EBITDA improvement.
Learn how to improve EBITDA by 6 to 7 figures annually by moving from commission-based advisory to transparent, aligned partnership. The decision isn't between good brokers and better brokers. It's between brokers who profit from your cost increases and partners who profit from your cost reduction.
Your next step: contact us for a preliminary healthcare cost analysis. We'll review your current spend, identify immediate optimization opportunities, and show you exactly what an aligned partnership would deliver for your enterprise.
